Counterparty risk is the chance that the other party to a contract fails to pay or deliver what it owes. It concentrates in OTC derivatives, securities financing, and trade credit. Banks control it with due diligence, netting, collateral, exposure limits, and central clearing, then price the residual through credit valuation adjustments.
On September 15, 2025, auto-parts maker First Brands Group quietly stopped forwarding customer payments it was collecting for Jefferies’ Point Bonita Capital fund. Two weeks later the company filed for Chapter 11, and Jefferies disclosed $715 million of receivables exposure in an SEC filing.
The receivables were due from blue-chip obligors like Walmart and AutoZone, yet the risk sat with the servicer in the middle. Bankruptcy advisors began investigating whether some invoices had been factored more than once, per Banking Dive’s reporting. That is counterparty risk in its purest form.
| Counterparty Risk: Key Takeaways |
| The BIS counted $846 trillion of notional OTC derivatives at mid-2025; netting cuts the real credit exposure to about $3 trillion. |
| Jefferies’ Point Bonita fund had $715 million frozen when First Brands failed in September 2025, a servicer-risk lesson for every treasurer. |
| The Basel Committee’s December 2024 counterparty risk guidelines replace 1999-era practice: continuous due diligence, complementary metrics, stress tests. |
| Top dealers held a record $1.6 trillion of initial and variation margin at year-end 2025 (ISDA); losses now hide in the uncollateralized tail. |
| S&P Global logged 145 corporate defaults in 2024; spreads move earlier than downgrades, so wire limits to both. |
| Nonbanks hold 51% of global financial assets ($256.8 trillion, FSB), so counterparty files must cover funds and NBFIs, not just banks. |
What follows prices the exposure with 2026 data from the BIS, ISDA, S&P Global, and the FSB. Ahead: the exposure types, the measurement toolkit, the controls regulators now demand, and the monitoring KRIs that catch a weakening counterparty early, with thresholds attached.
What Counterparty Risk Means in Practice
First Brands shows the definition in motion. The OCC frames counterparty risk as the chance the other side defaults before a transaction’s final settlement. Unlike a loan, the exposure is uncertain, because market moves keep changing what the defaulting side would owe.
The risk lives wherever obligations stretch over time. Swaps, forwards, repos, securities lending, and unhedged trade credit all carry it, and a currency swap can flip from asset to liability in a quarter. Bilateral OTC trades concentrate it because no clearinghouse stands in the middle.
Treasurers see the same exposure outside dealing rooms. The Association of Corporate Treasurers lists deposits, receivables, and supplier prepayments among everyday counterparty positions. A supplier risk management program is often the corporate twin of a bank’s dealer limit framework, run from the finance function.
| Instrument or relationship | Exposure window | Typical control | Who worries |
| Interest rate or FX swap | Life of the trade | Netting plus daily margin | Dealer credit desk |
| Repo and securities lending | Overnight to term | Haircuts and collateral | Funding desk |
| Trade receivables | 30 to 90 days | Factoring, credit insurance | Corporate treasurer |
| Bank deposits | On demand | Counterparty limits, spread | CFO and treasury |
| Structured trade finance | Program life | Servicer controls, audits | Fund investors |
Why the Numbers Demand Board Attention
The scale explains the supervisory pressure. The BIS counted $846 trillion of notional OTC derivatives outstanding at end-June 2025, up 16 percent in one year. Gross market value reached $21.8 trillion, and netting collapsed that to roughly $3 trillion of credit exposure.
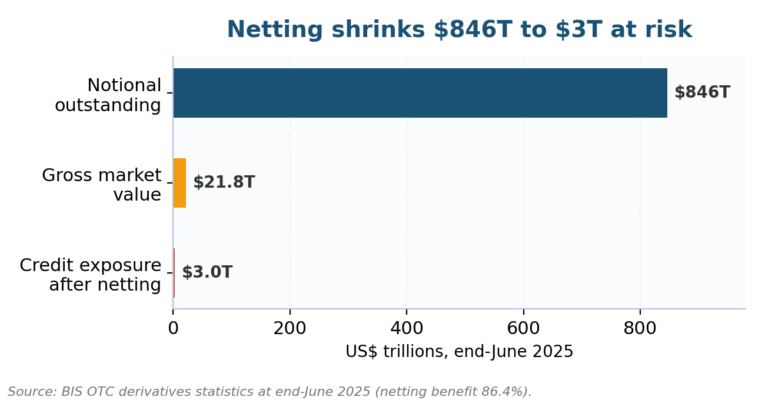
Figure 1. Close-out netting removed 86.4 percent of mark-to-market exposure at mid-2025, per the BIS.
Who sits on the other side is shifting. The FSB’s 2025 monitoring report puts nonbank financial intermediation at $256.8 trillion, 51 percent of global financial assets, growing twice as fast as banks. Hedge funds and private credit now dominate many dealers’ exposure queues.
Default math stayed uncomfortable too. S&P Global recorded 145 corporate defaults in 2024, down only slightly from 153 the year before. Any of those names could have been a swap counterparty, a supplier, or the bank holding your operating cash today.
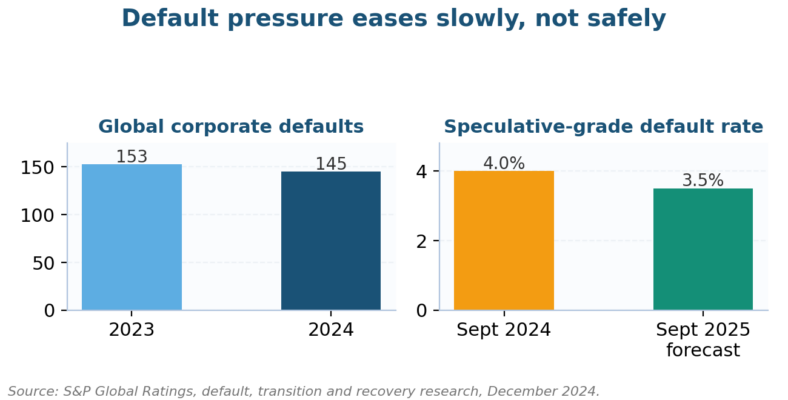
Figure 2. Defaults eased to 145 in 2024, with the speculative-grade rate forecast at 3.5 percent by September 2025.
From Pre-Settlement to Wrong-Way: Mapping the Types
Scale only matters once you know which flavor of default you face. Pre-settlement risk runs for the life of a trade, while settlement risk compresses into a single dangerous day. Credit risk deterioration usually arrives first and gives monitoring teams their early window.
| Type | What it means | Classic trigger |
| Pre-settlement risk | Default before a future obligation falls due | Counterparty downgrade mid-trade |
| Settlement risk | You deliver; the other side never does | Time-zone gaps, failed transfers |
| Replacement cost risk | Re-hedging the trade at worse prices after default | Volatile markets at default |
| Credit deterioration | Weakening financial health of the counterparty | Leverage creep, funding stress |
| Legal and documentation risk | Contracts unenforceable when tested | Netting void in a jurisdiction |
| Sovereign risk | A state or state entity stops paying | Capital controls, sanctions |
| Wrong-way risk | Exposure rises as the counterparty weakens | Collateral correlated with the name |
Wrong-way risk breaks the diversification logic that the other six types obey. Exposure grows exactly when the counterparty weakens, the pattern regulators flagged after 2008 and again in the 2021 family-office failures. Market risk and geopolitical risk often supply the underlying correlation.
How Dealers Measure What a Default Would Cost
Typing the risk sets up the harder question of size. Dealers track current exposure, potential future exposure, and expected positive exposure across netting sets, then charge trades a credit valuation adjustment. Liquidity risk enters through the collateral you would need to post in stress.
| Metric | Question it answers | Typical horizon |
| Current exposure (CE) | What would default cost today? | Spot |
| Potential future exposure (PFE) | How bad could it get at high confidence? | Trade life, 95th-99th percentile |
| Expected positive exposure (EPE) | What is the average exposure over time? | One year, regulatory |
| Credit valuation adjustment (CVA) | What is the market price of this default risk? | Trade life |
| CDS spread and rating | How does the market score the name? | Continuous |
Ratings and spreads stay useful as outside opinions, and banks managing credit risk lean on both. They move on different clocks, though. Spreads reprice daily while rating committees deliberate, so limit frameworks should treat a widening spread as the earlier signal.
Measurement matters only when the outputs move limits. Institutions managing interest rate risk learned to pair every metric with an action, and counterparty desks should copy that discipline. Treat every one of the following as a same-week limit review trigger:
- CVA on one name doubling inside a quarter
- Potential future exposure breaching 80 percent of the approved limit
- A counterparty’s CDS spread widening 50 percent faster than its sector
- Collateral disputes recurring with the same counterparty two months running
- Concentration above 10 percent of total exposure in one name or sector
How to Manage Counterparty Risk: Netting, Margin, Clearing
The control stack starts with paper and ends with capital. The Basel Committee’s final guidelines, published December 11, 2024, replace 1999-era guidance and demand due diligence at onboarding and through the relationship. They also require exposure measured through several complementary metrics, checked by routine stress tests.
Collateral is the working control between annual reviews. ISDA’s latest margin survey shows top dealers held $1.6 trillion of initial and variation margin at year-end 2025, with initial margin up 21.7 percent. Central counterparties collected another $423.5 billion for cleared rates and credit trades.
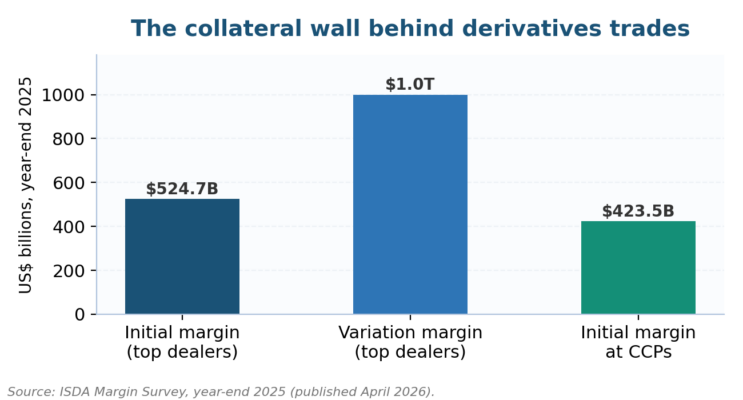
Figure 3. Dealers and CCPs now hold about $2 trillion of margin against derivatives exposure, ISDA’s survey shows.
Structure the rest around the BCBS practices and your own risk appetite statements. Netting agreements shrink gross exposure by 86.4 percent across the market, the BIS calculates. Clear standardized trades centrally, collateralize the rest, and cap single names inside the risk register.
- Run full due diligence at onboarding and refresh it on a fixed cycle
- Set a credit risk mitigation strategy per counterparty class: netting, collateral, guarantees
- Measure exposure with several metrics that cross-check each other, never a single model output
- Stress-test exposures against correlated market and credit shocks
- Give the counterparty framework a named senior owner and a board reporting line
| Control | What it does | Watch-out |
| ISDA master netting | Collapses gross claims to one net amount | Enforceability varies by jurisdiction |
| Credit support annex | Moves collateral as exposure moves | Disputes and threshold gaps |
| Central clearing | CCP absorbs bilateral default risk | Concentrates risk in the CCP |
| Exposure limits | Caps loss to any single name | Stale if reviewed annually |
| Hedging with CDS | Transfers default risk for a premium | Adds a new counterparty |
| Trade credit insurance | Covers receivables default | Exclusions bite in systemic events |
A fuller treatment of governance sits in our counterparty risk management guide, including committee design and reporting cadence. Regulatory compliance in banking supplies the supervisory frame. Use the two together: this page sizes the exposure, and that one runs the program.
What Lehman and First Brands Teach
Controls read differently once you price the failures. Lehman Brothers entered bankruptcy in September 2008 as counterparty to 906,000 derivative transactions under 6,120 ISDA master agreements, documented in Stanford Law Review analysis. Its counterparties spent years untangling terminations, valuations, and disputed collateral claims.
Barings Bank collapsed in 1995 from a single trader’s hidden positions, a reminder that your counterparty’s operational risks become your credit problem. Nothing about the bank’s balance sheet predicted the failure. Due diligence that stops at financial statements misses exactly this class of loss.
First Brands adds the 2025 chapter: servicer risk inside structured trade finance. Point Bonita’s receivables were owed by investment-grade retailers, yet $715 million froze when the middleman failed, and advisors probed possible double-factoring, according to Jefferies’ investor update. Exposure analysis must map who actually touches the cash.
| Case | Year | Loss channel | Lesson |
| Lehman Brothers | 2008 | 906,000 open derivative trades | Netting and docs decide recovery speed |
| Barings Bank | 1995 | Hidden trading by one employee | Operational failure becomes credit loss |
| First Brands | 2025 | $715M frozen receivables at Point Bonita | Map the cash path, not just the obligor |
Monitoring turns lessons into routine, and key risk indicator examples for counterparties are well established. Build the watch list from data you refresh monthly, then wire each indicator to a named escalation owner. Five belong on nearly every counterparty dashboard:
- Credit spread or CDS level versus the counterparty’s rating band
- Collateral dispute count and average resolution days
- Share of exposure not covered by netting or margin
- Days since the last full financial review of each material name
- Wrong-way flags: exposure rising alongside the counterparty’s stress signals
Common Counterparty Risk Questions Practitioners Ask
What is counterparty risk in simple terms?
Counterparty risk is the chance that whoever sits on the other side of your deal fails to pay or deliver. If a swap partner defaults or a customer misses invoices, you absorb the loss. The exposure exists in any promise that settles later than today.
How does counterparty risk differ from credit risk?
Credit risk covers any chance a borrower fails to repay, while counterparty risk is its two-sided, market-driven cousin, as Risk.net’s definition notes. In a derivative, either party can end up owing, and the amount swings daily with prices and rates. That uncertainty is why dealers model exposure distributions instead of reading a loan balance off a statement.
How do central counterparties reduce counterparty risk?
A central counterparty steps between the two sides of a cleared trade, becoming buyer to every seller and seller to every buyer. It collects margin daily and mutualizes losses through a default fund. CCPs held $423.5 billion of initial margin at the end of 2025, up 8.7 percent on the year.
What is wrong-way risk in counterparty exposure?
Wrong-way risk means your exposure to a counterparty grows at the same time its ability to pay shrinks. Selling put options on your own funding currency is the textbook case. Supervisors ask for specific wrong-way identification because netting and collateral models quietly assume the correlation away.
How do banks measure counterparty credit risk?
Banks measure counterparty credit risk with layered metrics: current exposure, potential future exposure, expected positive exposure, and a credit valuation adjustment charged to each trade. The Basel Committee’s 2024 guidelines direct firms to use several complementary measures and to stress-test them against correlated shocks.
Does counterparty risk exist outside financial markets?
Yes. Any business that ships goods before payment, prepays a supplier, or parks cash in one bank carries counterparty risk. First Brands’ 2025 bankruptcy hit trade finance funds, retailers’ supply chains, and lenders at once, which is why treasurers manage the exposure alongside banks.
The Traps That Sink Counterparty Programs
Programs rarely die from missing models. They die from governance gaps that the table below catalogs, each paired with a correction already proven at supervised banks. Test your own framework against the five before the next limit committee meeting convenes.
| Trap | Why it persists | Correction |
| Rating-only monitoring | Ratings lag the market by weeks | Add spread and CDS triggers to limits |
| Netting assumed enforceable | Legal review skipped by jurisdiction | Obtain netting opinions per country |
| Concentration creep | Limits set once, never rebalanced | Quarterly top-10 exposure review |
| Static annual reviews | Due diligence treated as onboarding-only | Continuous monitoring per BCBS 2024 |
| Ignoring the cash path | Obligor quality mistaken for program quality | Trace servicers and intermediaries |
The Road Through 2027
The next two years belong to nonbank exposure. The FSB’s monitoring keeps widening, and the Basel guidelines name NBFI counterparties as the priority case, so expect supervisors to ask for fund-level transparency that onboarding files rarely hold. Technology risk reviews are joining the credit file.
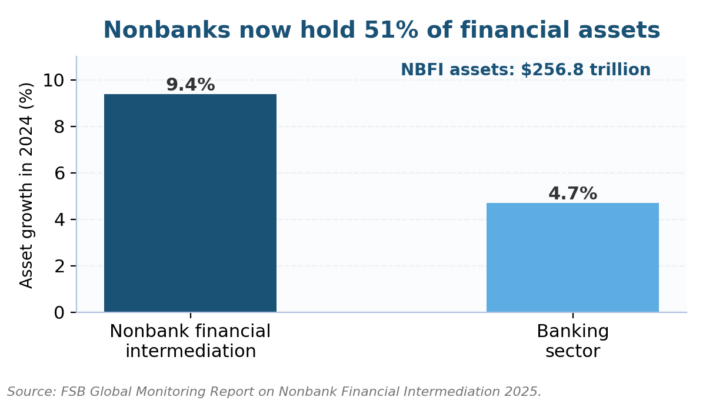
Figure 4. Nonbanks grew 9.4 percent in 2024 against 4.7 percent for banks, the FSB’s 2025 report shows.
Margin coverage will keep climbing from its record $1.6 trillion, and clearing mandates keep pulling standardized trades onto CCPs, tracked in ISDA’s market analysis. The bilateral tail that remains is the risky part. Price it, collateralize it, and give geopolitical scenarios a formal seat in the stress suite.
Trade finance needs the closest watch after First Brands. Receivables programs blend financial risk in ways standard taxonomies miss, and double-pledged collateral only surfaces in bankruptcy. Ask every structured counterparty one question early: who controls the cash flow path, and who checks?
Treasury and risk teams that want the framework in place can shortcut the build. We map counterparty exposures, set limit structures, and draft the board pack against ISO 31000 and the BCBS guidelines. Browse our services or contact us; most limit frameworks take under a month.
Chris Ekai is a Risk Management expert with over 10 years of experience in the field. He has a Master’s(MSc) degree in Risk Management from University of Portsmouth and is a CPA and Finance professional. He currently works as a Content Manager at Risk Publishing, writing about Enterprise Risk Management, Business Continuity Management and Project Management.