How does Germany manage risk? Through separate, legally mandated institutions rather than one central register: a constitutional debt brake for fiscal risk, the Finanzagentur for sovereign debt, BaFin and the Bundesbank for financial stability, the BSI for cyber risk, and the BBK for civil protection, with section 91 AktG and StaRUG binding company boards.
On 18 March 2025, 513 of the Bundestag’s 733 members voted to amend the Basic Law and loosen the debt brake, according to CNBC’s report from the chamber. The vote exempted defence spending above 1% of GDP and authorised a EUR 500 billion special fund for infrastructure and climate neutrality.
That single afternoon rewrote the fiscal-risk rule Germany had defended since 2009. It also explains why the rest of the system matters more now: when the borrowing constraint loosens, the debt agency, the supervisors, and the resilience authorities carry more of the load. The sections below take each one in turn with the 2026 figures. The sections below take each one in turn with the 2026 figures, so that the question of how does Germany manage risk gets an institution-by-institution answer.
| How Does Germany Manage Risk: Key Takeaways |
| Germany manages risk through a constitutional fiscal rule, an independent debt agency, two financial supervisors, a federal cyber authority, and a civil-protection office, each with its own statute rather than one national risk register. |
| On 18 March 2025 the Bundestag voted 513 to 207 to loosen the debt brake, exempting defence spending above 1% of GDP and creating a EUR 500 billion infrastructure and climate fund that runs for twelve years. |
| The Bundesbank reported on 31 March 2026 that general government debt reached EUR 2.84 trillion, or 63.5% of GDP, and the Finance Ministry’s own plan takes the ratio to 80.25% by 2029. |
| The Finanzagentur plans about EUR 512 billion of issuance in 2026: EUR 318 billion in capital-market auctions, EUR 176 billion in Treasury discount paper, and EUR 16 to 19 billion in green securities. |
| Financial stability rests on a 0.75% countercyclical capital buffer and a 1% sectoral buffer on residential mortgages, with BaFin’s 2026 Risks in Focus warning that stability is more likely to be tested. |
| The BSI registered 119 new vulnerabilities per day in its 2025 report, 24% more than a year earlier, and the NIS2 implementation act brought roughly 30,000 entities into scope on 6 December 2025. |
| Corporate Germany answers to section 91(2) AktG and section 1 StaRUG, which require boards to detect developments that threaten the company’s survival and to report them to the supervisory body without delay. |
How Does Germany Manage Risk Across Government?
Ask how does Germany manage risk across government and the answer is federal and statutory. Each risk domain has a named office, a founding law, and a reporting line to the Bundestag, which is a different design from a single national enterprise risk management framework with one owner. The 2023 National Security Strategy, titled Integrated Security for Germany, is the closest thing to an umbrella document.
That strategy names three pillars: defence, resilience, and sustainability. It treats supply chains, raw materials, critical infrastructure, and disinformation as security matters, which is why geopolitical risk now runs through the fiscal, financial, and civil-protection agencies at once, with the Foreign Office as one voice among several. That doctrine now shapes how the agencies that help Germany manage risk set their priorities.
| Risk domain | Lead institution | Founding rule | Primary 2026 output |
| Fiscal | Federal Ministry of Finance | Basic Law Articles 109 and 115 (debt brake) | Federal budget and fiscal plan to 2029 |
| Sovereign debt | Deutsche Finanzagentur | Owned by the Federal Republic via the Finance Ministry | Annual issuance outlook, about EUR 512 billion |
| Financial stability | Bundesbank, BaFin, Financial Stability Committee | Financial Stability Act (FinStabG) | Financial Stability Review, Risks in Focus, buffer decisions |
| Cyber | Federal Office for Information Security (BSI) | BSI Act and the NIS2 implementation act | State of IT Security report, NIS2 registry |
| Civil protection | Federal Office of Civil Protection (BBK) | Civil Protection and Disaster Assistance Act (ZSKG) | Risk analysis report to the Bundestag |
| Corporate | Management and supervisory boards | Section 91 AktG, section 1 StaRUG | Early risk detection system, auditor’s PS 340 opinion |
The table is the map for everything that follows on how the institutions that help Germany manage risk fit together. In our reading, the design trades speed for legitimacy: no single official can move money, capital buffers, or emergency powers, but every move leaves a paper trail that a court or a parliamentary committee can later examine. That trade shaped the Ahr valley inquiry discussed below.
Why Fiscal Risk Still Starts With the Debt Brake
The debt brake limits the federal structural deficit to 0.35% of GDP and, until 2025, barred the sixteen Länder from structural borrowing at all. The March 2025 amendment, summarised by Noerr’s analysis of the Bundestag vote, kept that core rule but carved three exceptions around it. The brake is the first place to look when asking how does Germany manage risk in the public finances.
- Defence, civil protection, intelligence, and cyber spending above 1% of GDP no longer count against the borrowing limit.
- A EUR 500 billion special fund for infrastructure and climate neutrality sits outside the brake for twelve years, with EUR 100 billion reserved for the Länder and EUR 100 billion for the Climate and Transformation Fund.
- The Länder may now collectively borrow 0.35% of GDP in structural terms, matching the federal allowance.
The Bundesrat confirmed the package on 21 March 2025 with 53 votes, above the 46 required. Clean Energy Wire’s summary notes the fund can approve projects for twelve years, so the borrowing decision made in 2025 will shape the debt path well past 2037. That long tail is the fiscal risk worth watching, and it tests how well the debt brake still helps Germany manage risk over a full political cycle.
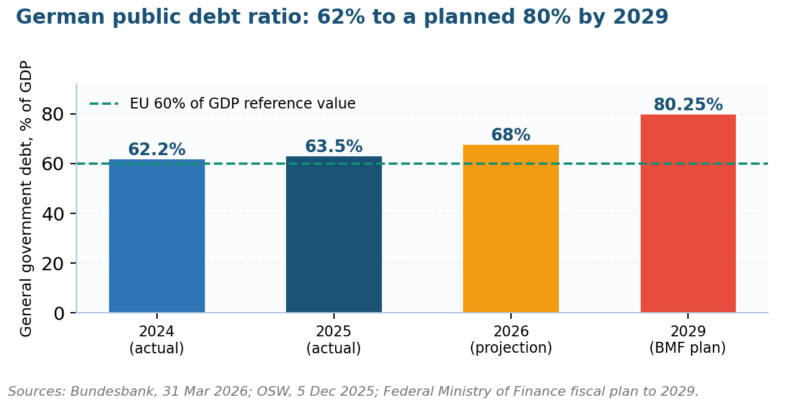
Figure 1. The debt ratio crossed the EU 60% reference value in 2024 and the government’s own plan takes it above 80% by 2029.
The numbers already show the change, and they are the first evidence of how the amended brake lets Germany manage risk with more borrowing room. The Bundesbank reported on 31 March 2026 that general government debt rose EUR 144 billion in 2025 to EUR 2.84 trillion, lifting the ratio from 62.2% to 63.5% of GDP. The federal level alone added EUR 107 billion.
Destatis then recorded a EUR 71.3 billion deficit for the first half of 2026, or 3.1% of GDP, with expenditure up 6.1% against revenue up 2.8%. The Finance Ministry’s own fiscal plan, cited by OSW’s budget analysis, projects the debt ratio at 80.25% of GDP by 2029.
| Fiscal indicator | 2024 | 2025 | Latest or planned |
| General government debt | EUR 2.69 trillion | EUR 2.84 trillion | Rising with the special fund |
| Debt ratio, % of GDP | 62.2% | 63.5% | About 68% in 2026; 80.25% by 2029 (plan) |
| Maastricht deficit | Below 3% | EUR 119 billion | 3.1% of GDP in H1 2026 |
| Federal net borrowing | EUR 50.5 billion | Higher, special funds active | Over EUR 180 billion in 2026 including special funds |
| Special fund spending | None | Fund operational from October 2025 | EUR 58 billion planned for 2026 |
The special fund’s first full year is 2026. The Federal Government’s fund page lists EUR 58 billion drawn from it within a EUR 120 billion investment programme, with rail maintenance, bridges, hospitals, and broadband prioritised. Whether that spending lands on time is the execution risk the Finance Ministry now carries alongside the borrowing risk. Both questions sit inside the larger one of how does Germany manage risk when the money is easier to borrow than to spend.
Sovereign Debt: How the Finanzagentur Runs the Book
The Deutsche Finanzagentur is a limited company wholly owned by the Federal Republic and steered by the Finance Ministry. It borrows on the federal government’s behalf, manages the outstanding portfolio, and runs the auctions through which Bunds set the euro area’s benchmark yield curve. On sovereign debt, it is the practical answer to how does Germany manage risk.
Its issuance outlook published on 18 December 2025 plans roughly EUR 512 billion for 2026: EUR 318 billion through capital-market auctions, EUR 176 billion through Treasury discount paper, and EUR 16 to 19 billion in green securities. Four syndicated deals are planned, including the first 20-year Federal bond.
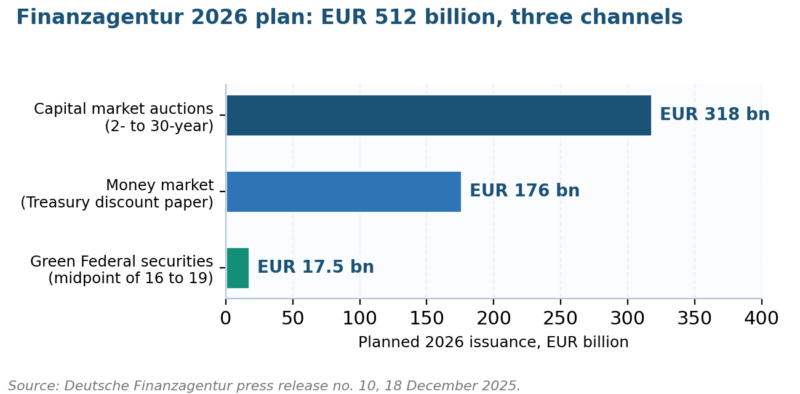
Figure 2. Capital-market auctions carry the bulk of 2026 funding, with money-market paper covering the shorter end and green securities a small, growing slice.
| Instrument | 2026 volume | Auction pattern | Risk it manages |
| 2-year Federal Treasury notes (Schatz) | EUR 92 billion | 17 issues, quarterly new lines to EUR 22 billion each | Rollover concentration at the short end |
| 5-year Federal notes (Bobl) | EUR 73 billion | 14 issues, two new series | Mid-curve refinancing |
| 7-year Federal bonds | EUR 22 billion | Six dates, one new line in October | Maturity gap between 5 and 10 years |
| 10-year Federal bonds (Bund) | EUR 82 billion | 15 auctions, two new lines to about EUR 40 billion each | Benchmark liquidity and interest-rate risk |
| 15-, 20- and 30-year bonds | EUR 49 billion | Multi-ISIN taps, first 20-year via syndicate | Duration extension to lock in rates |
| Treasury discount paper (Bubill) | EUR 176 billion | Monthly 12-month lines plus reopenings | Cash-flow timing and liquidity |
The maturity ladder is the risk tool that lets Germany manage risk on refinancing. Spreading EUR 318 billion across six segments limits how much must be refinanced in any one year, and the new 20-year line lengthens average maturity while long-end demand exists. This is the same logic a treasurer applies to counterparty risk, scaled to a sovereign.
One correction to the record: the earlier version of this article described cash arrangements with the Reserve Bank of New Zealand. Those belong to the New Zealand Treasury, not Germany. The Finanzagentur’s liquidity management runs through the Bundesbank and the money market, and any description of how the Finanzagentur helps Germany manage risk, or of risk in finance at sovereign level should start there.
Financial Stability: BaFin, the Bundesbank, and the Buffers
Financial supervision is split. BaFin licenses and supervises banks, insurers, and securities firms; the Bundesbank conducts ongoing prudential monitoring and publishes the annual Financial Stability Review; and the Financial Stability Committee sets macroprudential buffers under the countercyclical capital buffer rules. Since 2014 the European Central Bank has directly supervised the largest German banks. That split is the first thing to grasp about how does Germany manage risk in finance: no single supervisor holds the whole picture.
The Bundesbank’s Financial Stability Review of 6 November 2025 kept the countercyclical buffer at 0.75% and the sectoral systemic risk buffer on residential mortgages at 1%, after cutting the latter from 2% in April 2025. It also warned that non-performing loans had risen steadily since late 2022, led by commercial real estate.
| Macroprudential tool | Current setting | Set by | What it targets |
| Countercyclical capital buffer | 0.75% of risk-weighted assets | BaFin on Financial Stability Committee advice | Credit-cycle losses across all domestic exposures |
| Sectoral systemic risk buffer | 1% (cut from 2% in April 2025) | BaFin | Residential real estate loan losses |
| Bundesbank simplification proposal | Merge the two buffers | Proposed November 2025 | Double counting that blunts buffer use |
| Credit risk monitoring | Supervisory priority for 2026 | BaFin Risks in Focus | Corporate loan books amid rising insolvencies |
BaFin’s Risks in Focus 2026, published 28 January 2026, named six top risks, including non-performing loans, private debt fund interconnections, and stablecoin volatility. BaFin President Mark Branson said the risk that financial stability would be put to the test was increasing. The report also counted 5.7 million over-indebted consumers in November 2025.
The corporate side supports that caution. Destatis recorded 24,064 corporate insolvencies in 2025, up 10.3% and the highest count since 2014, with December alone up 14%. For a bank, that is the loss-given-default problem discussed in how banks manage credit risk, arriving in volume.
We think the buffer settings are defensible but the risk weights are the softer point. The Bundesbank itself noted that systemically important banks’ risk weights remain low despite worse conditions, which means headline capital ratios overstate resilience in parts of the system. A risk appetite statement built only on ratios would miss that. Anyone asking how does Germany manage risk in banking should look at the weights before the ratios.
How Does Germany Manage Risk in Cyberspace? The BSI and NIS2
The Federal Office for Information Security, the BSI, is the national cyber authority and the institution that helps Germany manage risk in the digital domain. Its State of IT Security in Germany 2025 report, covering July 2024 to June 2025, registered an average of 119 new vulnerabilities per day, 24% more than the prior year, alongside 280,000 new malware variants daily and 950 reported ransomware cases.
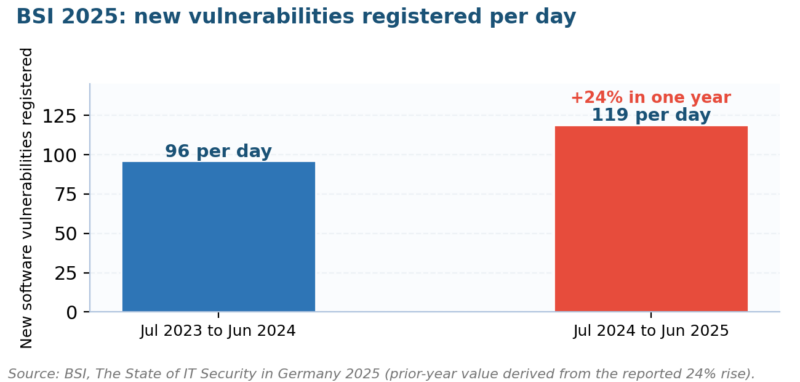
Figure 3. The BSI counted 119 new vulnerabilities per day in its 2025 reporting period, up 24% year on year.
The legal machinery changed on 6 December 2025 when the NIS2 implementation act entered into force. Noerr’s cybersecurity briefing describes a three-stage incident regime with no transitional period: an initial report within 24 hours, an update within 72 hours, and a final report within one month, all filed through the BSI portal. Reporting deadlines, not voluntary guidance, are now how the BSI helps Germany manage risk from cyber incidents.
| NIS2 element in Germany | Rule | Threshold or deadline | Who enforces |
| Scope | Essential and important entities in 18 sectors | About 30,000 entities from 6 December 2025 | BSI |
| Essential entity size | Large enterprises | 250 or more staff, or over EUR 50 million revenue | BSI registration portal |
| Important entity size | Medium enterprises | 50 or more staff, or over EUR 10 million revenue | BSI registration portal |
| Incident reporting | Three-stage notification | 24 hours, 72 hours, one month | BSI |
| Management duties | Approve and oversee risk measures; training | Training refreshed every three years | Personal liability under the act |
| Physical resilience | KRITIS umbrella act (CER Directive) | In force 17 March 2026 | BBK and sector regulators |
The OpenKRITIS project counts roughly 30,000 entities across 18 sectors now in scope, split into KRITIS operators, essential entities, and important entities by headcount and turnover. That is an order of magnitude more organisations than the old IT Security Act covered, and most of them have never run a formal cybersecurity risk management programme. For those firms, the question of how does Germany manage risk has just become a question about their own boardroom.
Physical resilience followed. The KRITIS umbrella act, analysed by A&O Shearman, took effect on 17 March 2026 and transposes the EU Critical Entities Resilience Directive. A German utility now has separate cyber and physical statutes with one shared business impact analysis underneath both, and our DORA versus NIS2 comparison shows how banks reconcile the overlap. Together the two statutes show how layered the answer to how does Germany manage risk has become for infrastructure operators.
Civil Protection: What the Ahr Valley Changed at the BBK
Peacetime disaster response belongs to the Länder; the Federation handles civil defence and coordinates through the BBK. The European Commission’s country profile puts the volunteer base at more than 1.8 million people across fire services, the THW technical relief agency, and aid organisations, which is the largest such reserve in Europe. That division of labour is central to the way the federal system lets Germany manage risk from natural hazards, and it is where the 2021 flood found the gap.
The night of 14 to 15 July 2021 exposed the system’s weak point. The Ahr valley flood killed 134 people in the valley and 188 nationally, and deutschland.de’s reconstruction account records 3,000 of 4,200 riverside buildings damaged and a EUR 30 billion federal reconstruction fund. The district’s evacuation order went out at 23:09, after the water had already risen.
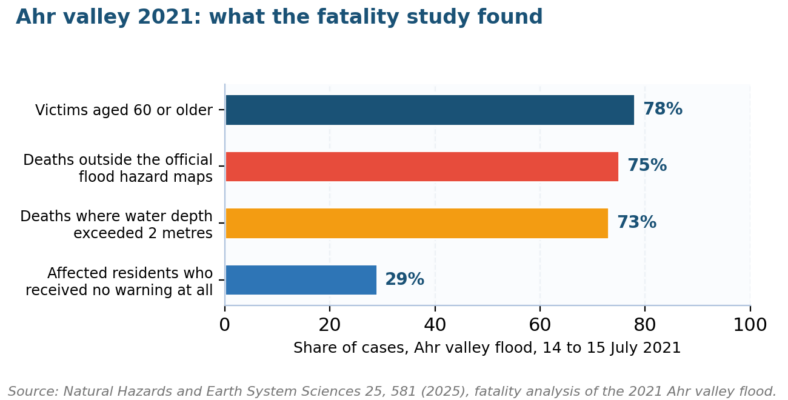
Figure 4. Three quarters of the Ahr valley deaths occurred outside the official hazard maps, and 29% of affected residents received no warning.
The fatality study published in Natural Hazards and Earth System Sciences found that 75% of deaths occurred outside the mapped hazard zones, 73% where water exceeded two metres, and 78% among people aged 60 or older. The forecast had predicted a 5.74 metre peak at Altenahr; the river reached about 10.2 metres.
| Ahr valley failure | What the inquiry found | System change since |
| Hazard maps | Three quarters of deaths outside the mapped zone | Map revisions and extreme-scenario mapping in Rhineland-Palatinate |
| Warning chain | 29% of affected residents received no warning | Cell broadcast rolled out nationally from February 2023; annual warning day |
| Local decision-making | Disaster alert declared shortly before midnight | State inquiry of 42 hearings and a 2,100-page report; criminal proceedings examined |
| Vulnerable residents | 78% of victims aged 60 or over; 16% with impairments | Evacuation planning for care homes and campsites |
| Reconstruction finance | EUR 30 billion fund authorised in 2021 | Fund still disbursing; bridges and rail rebuilt to higher flood lines |
The BBK’s formal tool for helping Germany manage risk is the risk analysis under section 18 ZSKG, reported to the Bundestag each year. The 2025 report, tabled on 22 January 2026, modelled chemical warfare agent attacks on a seaport, a rail yard, and a Bundeswehr depot, with more than 8,500 deaths in the first 15 hours of the scenario and hospital capacity overwhelmed.
That shift from floods and pandemics to wartime scenarios is the clearest signal of where German civil protection is heading. The report’s own recommendations include CBRN protective equipment for hospitals and emergency services and a federal agency for chemical hazards. Our guide to national disaster risk management sets out the comparable US structure under FEMA. It is also the point where the question of how does Germany manage risk stops being a civil matter and becomes a defence one.
How Does Germany Manage Risk at Company Level? AktG and StaRUG
At company level, the answer to how does Germany manage risk is a board duty that predates ISO 31000. Section 91(2) of the Stock Corporation Act, inserted by the 1998 KonTraG reform, requires the management board to set up a monitoring system so that developments threatening the company’s survival are detected early. Section 91(3) adds an internal control and risk management system for listed companies.
The 2021 restructuring law widened the net. Section 1 StaRUG obliges the managers of every limited-liability entity, including each GmbH, to monitor continuously for developments that could endanger the company’s existence, to take countermeasures, and to report to the supervisory body without delay. A GmbH with twenty staff is covered.
| German rule | Who it binds | Core requirement | Evidence expected |
| Section 91(2) AktG (KonTraG, 1998) | Management boards of stock corporations | Early detection of survival-threatening developments | Documented early risk detection system |
| Section 91(3) AktG (FISG, 2021) | Listed companies | Appropriate and effective internal control and risk management system | Board assessment reported to the supervisory board |
| IDW PS 340 (revised) | Auditors of listed companies | Audit of the early detection system, including risk aggregation | Auditor opinion covering risk-bearing capacity |
| Section 1 StaRUG (2021) | Managers of all limited-liability entities | Continuous crisis monitoring, countermeasures, immediate reporting | Minutes and reports to the supervisory body |
| Supply Chain Act (LkSG, amended 2025) | Companies with 1,000 or more employees in Germany | Human-rights due diligence in own operations and direct suppliers | Risk analysis, policy statement, complaints channel |
The auditing standard is where theory meets method. The revised IDW PS 340, in force for financial years from 2021 and explained in RiskNET’s summary, expects risk aggregation through simulation and a stated risk-bearing capacity, replacing the qualitative matrix. That aligns with how we build risk management programs: aggregate first, then set appetite by sector. That simulation requirement makes auditors, not just regulators, part of the machinery that helps Germany manage risk in the corporate sector.
Supply chain duty narrowed in 2025. The 3 September 2025 amendment, summarised by KPMG Law, abolished the annual BAFA report and dropped environmental sanctions, while keeping the risk analysis, policy statement, and complaints channel for firms with 1,000 or more German staff. An enterprise supplier risk management program still has to exist; it just no longer files a report. Even narrowed, the duty shows how far the laws that help Germany manage risk reach into supply chains.
Practitioners comparing frameworks should note the direction of travel. German law asks for aggregation and survival thresholds, which is closer to COSO’s quantitative leanings than to ISO 31000’s process view. The ISO 31000 standard remains the reference vocabulary, but the auditor tests numbers, and the operational risk management register feeds them. The practical lesson from how does Germany manage risk in the corporate sphere is that aggregation, not classification, is what gets audited.
Your Questions on How Does Germany Manage Risk, Answered
At the national level, how does Germany manage risk?
The short answer to how does Germany manage risk nationally is through separate statutory institutions: the debt brake and Finance Ministry for fiscal risk, the Finanzagentur for sovereign debt, BaFin and the Bundesbank for financial stability, the BSI for cyber risk, and the BBK for civil protection. The 2023 National Security Strategy links them under the label of integrated security.
With public debt rising, how does Germany manage risk?
The constitutional debt brake still caps structural federal borrowing at 0.35% of GDP, but the March 2025 amendment exempted defence spending above 1% of GDP and a EUR 500 billion special fund. The Bundesbank puts debt at 63.5% of GDP for 2025, and the Finance Ministry’s plan reaches 80.25% by 2029. In short, the brake still helps Germany manage risk, but with wider exemptions than before.
Inside its banking system, how does Germany manage risk?
Banks face a 0.75% countercyclical capital buffer and a 1% sectoral buffer on residential mortgages, set on the Financial Stability Committee’s advice. The Bundesbank’s November 2025 review flagged rising non-performing loans, and BaFin’s 2026 Risks in Focus made credit risk a supervisory priority after 24,064 corporate insolvencies in 2025. That combination of buffers and supervisory priorities is how the system helps Germany manage risk inside the banking sector.
After NIS2, how does Germany manage risk in cyberspace, and who is in charge?
The NIS2 implementation act, in force since 6 December 2025, places about 30,000 entities under BSI oversight with 24-hour, 72-hour, and one-month incident reporting deadlines. The BSI’s 2025 report counted 119 new vulnerabilities per day, and the KRITIS umbrella act added physical resilience duties from 17 March 2026.
In what way does Germany manage risk from floods and disasters?
The Länder run peacetime disaster response, supported by more than 1.8 million volunteers, while the BBK coordinates federal civil protection and the annual risk analysis under section 18 ZSKG. After the 2021 Ahr valley flood killed 188 people, Germany rolled out cell broadcast warnings and revised hazard maps. Warnings and maps are now the front line of how the Länder and the BBK help Germany manage risk from floods.
Which laws decide how German companies manage risk?
Section 91(2) AktG requires stock corporation boards to run an early risk detection system, and section 1 StaRUG extends a continuous crisis-monitoring duty to every limited-liability company. Auditors test listed companies against IDW PS 340, which expects risk aggregation and a defined risk-bearing capacity in the auditor’s evidence. Those three instruments are the corporate answer to how does Germany manage risk.
What Goes Wrong and the Fixes That Work
| Pitfall | Root cause | Remedy |
| Treating the debt brake as the whole fiscal control | The rule caps structural borrowing but not special funds or the 1% defence carve-out | Track gross financing need and the special fund’s drawdown, not just the headline deficit |
| Reading capital ratios as resilience | Low risk weights at large banks flatter the ratio | Pair ratios with the Bundesbank’s risk-weight commentary and NPL trend |
| Assuming NIS2 is an IT problem | Management duties and personal liability sit with the board | Board training every three years, documented risk decisions, tested 24-hour reporting |
| Trusting the hazard map | Ahr valley: 75% of deaths outside mapped zones | Plan for the extreme scenario, not the statutory return period |
| Waiting for a warning | 29% of affected Ahr residents received none | Multi-channel warning plus local evacuation triggers tied to gauge readings |
| Running a qualitative risk matrix for the auditor | IDW PS 340 expects aggregation and risk-bearing capacity | Monte Carlo aggregation of the top risks against equity and liquidity |
| Copying another country’s framework | The earlier version of this article did exactly that | Cite the German statute and agency for every claim |
The Road to 2029: Higher Debt and a Wider Resilience Mandate
The fiscal path is set. Federal borrowing above EUR 180 billion in 2026, a special fund that runs to 2037, and a planned 80.25% debt ratio by 2029 mean the Finanzagentur’s issuance calendar becomes a permanent feature of European rates markets. Investors will watch the 20-year line and the green framework published in January 2026. Both are now permanent parts of how the debt office helps Germany manage risk.
Supervisors will keep tightening where the Bundesbank pointed. Expect the buffer merger proposal to reach the Financial Stability Committee, more scrutiny of commercial real estate exposures, and BaFin’s data-driven reviews to replace checklist supervision. A key risk indicator set for a German bank in 2026 should carry NPL migration and risk-weight density side by side. That is the direction in which supervisors will help Germany manage risk over the next three years.
Civil protection is being rebuilt around wartime scenarios. Section 18 ZSKG analyses of chemical attacks, the KRITIS umbrella act, and the defence carve-out all point the same way. For companies, that means scenario-based risk assessment should now include hostile-state disruption of ports, rail, and power, and crisis management plans should assume the state’s resources are committed elsewhere. It is the clearest sign yet that the answer to how does Germany manage risk is being rewritten around defence.
If you run risk for a subsidiary, supplier, or investor exposed to Germany, we can map your obligations under AktG, StaRUG, NIS2, and the KRITIS act and build the aggregation model an IDW PS 340 auditor will accept. Start with our services, then contact us to scope the review before the next audit cycle opens.
Chris Ekai is a Risk Management expert with over 10 years of experience in the field. He has a Master’s(MSc) degree in Risk Management from University of Portsmouth and is a CPA and Finance professional. He currently works as a Content Manager at Risk Publishing, writing about Enterprise Risk Management, Business Continuity Management and Project Management.